Nvidia (Nasdaq: NVDA) drew the market’s attention on Tuesday after Atif Malik, an analyst at Citi, reaffirmed the buy rating on the stock while upwardly revising its price target, citing a surge in capital investments in data centers and its technical edge over its rivals. With its cutting-edge technologies, Nvidia has positioned itself as a leader in the AI chip domain. This has bolstered its share price by about 210% so far this year. The stock of Nvidia closed Tuesday’s trading at $474.94, up $10.33 or 2.22% from the prior close.
The analyst highlights three main factors influencing amendments to the equity research team’s stock model.
These components are as follows:
- Increasing demand for GPUs (Graphics Processing Units)
- A better grasp of the competitive landscape, covering both tailor-made ASIC (Application-Specific Integrated Circuit) and AMD GPU (Graphics Processing Unit) usage in data centers
- Multiple reports on the effect of Generative AI from several worldwide cross-departments of Citi.
In a note to clients, Malik conveyed his conviction that there is an advantageous risk-reward scenario regarding growing year-on-year sales to data centers all throughout the year. However, he also identified several uncertainties in the short- to long-term, including the China supply restrictions, a potential slowdown in macroeconomic factors affecting gaming sector demand, and increased challenges from competitors.
Atif Malik has pointed out that Citi expects rapid growth in the artificial intelligence market. In this regard, the analyst believes that Nvidia is well-positioned to maintain its dominance in this market, outperforming its rivals.
Despite competition from AMD, the Citi analyst expects the continuation of Nvidia’s leadership in its sphere of operation. This is primarily attributed to Nvidia’s advantageous position in software that optimizes GPU calculations, its strong networking product portfolio, and its state-of-the-art hardware.
According to Citi, Meta’s PyTorch 2.0 machine-learning system has the potential to aid Advanced Micro Devices Inc. (AMD) in reducing the disparity between its application software and Nvidia’s. Still, Malik believes that Nvidia’s vast expertise in GPU optimization, gathered over the years utilizing CUDA, its software platform, and cuDNN, a neural-network library, may require several versions of competitor GPUs and program upgrades to be matched.
Therefore, according to the Malik-led analyst team, Nvidia will continue to hold a significant edge over AMD in terms of AI efficiency. Furthermore, they predict that Nvidia will retain a market share of approximately 90% in the AI-associated graphics-processing unit (GPU) domain for the upcoming two to three years. The analyst also projects that this lucrative AI chip market will command a value of $150 billion in another four years. Despite potential challenges such as increased US limitations on shipments to China and future competition from rivals, Citi remains supportive of the stock.
Atif Malik additionally highlighted the presence of several significant data center orders valued at $2 billion or higher. Furthermore, Malik stressed that he is well aware of the challenges posed by tailor-made ASIC and AMD chips in the data center arena, along with the overall growth of generative AI and its significant impact.
Based on the aforesaid arguments, Malik upwardly revised his earnings per share forecasts for FY 2024 by 6%. For FY25 and FY26, the analyst lifted the earnings per share expectations by 38% and 30%, respectively.
Furthermore, Atif Malik, expecting an exceptional performance fueled by generative AI sector growth, lifted the base-case price target of Nvidia to $520 per share, reflecting a PE (price-to-earnings) ratio of 35x from the previous guidance level of $420 per share, and also reaffirmed the buy rating. This is based on the assumption that generative AI-related workloads will grow by 100% in 2023.
In case a bull-case scenario is realized, Malik anticipates Nvidia stock to trade at $600 a share, reflecting a PE ratio of 40x. The best-case scenario presumes that sales will exceed expectations, primarily driven by advancements in generative AI technology. Additionally, it is anticipated that the macroeconomic environment will remain favorable, thereby making sure the gaming sector records sustained growth this year and next year without any significant contraction. Notably, the upwardly amended price targets have taken revised FY 2024, FY 2025, and FY 2026 EPS estimates into consideration.
The reaffirmation of the buy rating and upward revision of the price target are expected to keep the stock of Nvidia slightly bullish in the short term.
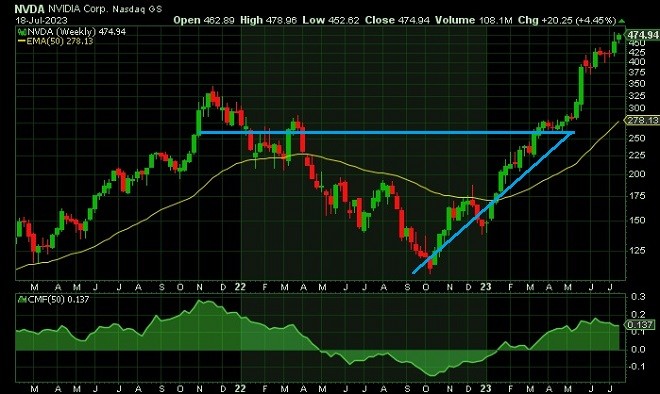
The historical price chart indicates that the stock of Nvidia is rising after breaking above the ascending triangle formation. The next major resistance is anticipated to be near 500. Minor support exists at 430. Additionally, the Chaikin Money flow indicator is showing a positive reading. Therefore, we anticipate Nvidia’s stock to remain in an uptrend in the short term.
Disclaimer: Any financial trading analysis offered here is our opinion and is not intended as advice or direction for investors. We cannot guarantee the success of any trades made as a consequence of this article, and we encourage traders to incorporate a strong money management strategy to limit losses when they enter the markets. Please use this article as part of your own research before formulating strategies prior to trading.