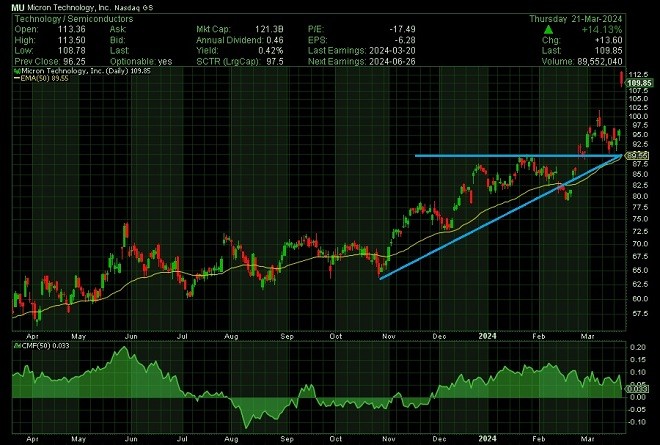
Micron Technology Inc. (Nasdaq: MU) reported better than anticipated fiscal 2024 second-quarter earnings and revenues. The company, capitalizing on the AI boom, also issued solid third-quarter revenue guidance. Following a swing to profit, the stock of Micron hit a new historical high of $113.50 before closing at $109.85, up $13.60, or 14.13%, from the prior close.
The Boise, Idaho-based company reported second-quarter revenues of $5.82 billion, up 57.70% from $3.69 billion in the second quarter of fiscal 2023.
For the second quarter, which ended February 29, 2024, Micron posted a net income of $793 million, or $0.71 per share, compared with a net loss of $2.31 billion, or $2.12 per share, in the quarter that ended March 2, 2023.
Excluding stock-based compensation, restructure and asset impairments, and patent cross-license agreement gain, among others, the 2Q 2024 non-GAAP net income was $476 million, or $0.42 per share, compared with a non-GAAP net loss of $2.08 billion, or $1.91 per share, in 2Q 2023. Notably, this is the first non-GAAP profit for the company after five consecutive loss-making quarters.
Analysts surveyed by LSEG had anticipated Micron to report a net loss of $0.25 per share on revenues of $5.35 billion.
Sanjay Mehrotra, President and CEO of Micron Technology, stated, “Micron delivered fiscal Q2 results with revenue, gross margin, and EPS well above the high end of our guidance range—a testament to our team’s excellent execution on pricing, products, and operations.”
The CEO revealed that Micron’s high-bandwidth memory (HBM) chips, essential components in the creation of intricate AI applications, have been fully booked up for 2024, with a significant portion of the supply for 2025 already earmarked.
Nvidia, a leading player in AI chip technology, has roped in Micron for its latest HBM 3E chips to be integrated into their upcoming H200 graphics processing units (GPUs). Previously, Nvidia had exclusively relied on South Korean chip giant SK Hynix as the exclusive supplier of HBM chips.
Mehrotra stated that Micron anticipates memory chip (DRAM and NAND) pricing levels to keep rising for the rest of this year.
Additionally, Mehrotra conveyed assurance that revenues from HBM are anticipated to contribute positively to Micron’s gross margins during the third quarter. Emphasizing this point, he reaffirmed the company’s projection of generating revenue of several hundred million dollars from these high-end chips in FY24.
Sumit Sadana, Micron’s Chief Business Officer, further disclosed that the company had inked deals with new clients for its HBM products, details of which have not yet been made public.
Looking ahead, Micron projects a non-GAAP gross margin of 26.50% (+/- 1.50%) in 3Q24, beating Wall Street forecasts of 20.80%.
Furthermore, the company anticipates Q3 revenues of $6.60 billion (+/- $200 million), higher than LSEG estimates of $6.03 billion. Likewise, Micron expects Q3 earnings per share of $0.45 (+/- $0.07).
The solid quarterly earnings report and Q3 guidance highlight rising demand for Micron’s high-tech memory chips and other state-of-the-art semiconductors as tech giants battle to gain an edge in the AI domain.
The earnings beat and solid Q3 outlook are expected to keep Micron’s stock slightly bullish in the near term.
The historical price chart indicates that the stock of Micron is ascending after consolidating above the ascending triangle. The stock is also trading above its 50-day moving average, while the Chaikin Money Flow indicator is showing a positive reading. Therefore, we anticipate Micron’s stock to remain in an uptrend in the near term.
Disclaimer: Any financial trading analysis offered here is our opinion and is not intended as advice or direction for investors. We cannot guarantee the success of any trades made as a consequence of this article, and we encourage traders to incorporate a strong money management strategy to limit losses when they enter the markets. Please use this article as part of your own research before formulating strategies prior to trading.