Foot Locker, Inc. (NYSE: FL) reported weak fiscal 2022 fourth-quarter results. However, the athletic footwear manufacturer’s quarterly earnings and revenue surpassed estimates. Also, the company’s comp recorded an increase. Furthermore, Foot Locker issued a weak FY 2023 outlook. The stock ended Tuesday’s trading session at $42.68, up $2.82 or 7.07% from its prior close.
The New York-based company reported fourth-quarter revenues of $2.33 billion, down 0.30% from $2.34 billion in a similar quarter of fiscal 2021. Analysts polled by Thomson Reuters had anticipated the company to report revenues of $2.15 billion.
For the fourth quarter, which ended January 28, 2023, Foot Locker recorded a net income of $19 million, or $0.20 per share, compared with a net income of $103 million, or $1.02 per share, in the quarter that ended January 29, 2022.
Excluding impairment and other charges, the Q4 2022 non-GAAP net income was $92 million, or $0.97 per share, down from $148 million, or $1.46 per share, in Q4 2021. Wall Street analysts forecast non-GAAP net income of $0.51 per share for the recent quarter.
The quarterly earnings report indicates that the gross margin fell by 290 basis points, primarily due to considerable discounts offered to boost sales. Comp sales rose by 4.20% on a y-o-y basis. The increase was driven by a rise in foot traffic and better access to top-notch inventory.
For FY 2023, which comprises 53 weeks, Foot Locker forecasts adjusted earnings of between $3.35 and $3.65 per share. This includes $0.15 from the additional week. Analysts polled by Reuters anticipate earnings of $4.15 per share for FY 2023. Notably, the company reported a non-GAAP income of $4.95 per share for FY 2022.
Furthermore, Foot Locker projects FY 2023 sales to decline by 3.50% to 5.50% from FY 2022. This includes roughly 1% of the additional week. Also, the company expects comparable sales to decline by 3.50% to 5.50%.
Notably, the company expects low- to mid-20s EPS growth beyond FY 2023. Specifically, for FY 2024 through FY 2026, Foot Locker expects sales to increase by 5% to 6%. Comparable sales are forecast to grow 3% to 4%.
The company’s Board approved a quarterly cash dividend of $0.40 per share, payable on April 28.
Foot Locker also unveiled the “Lace Up” initiative, which includes fresh strategies and financial goals. The company also revealed that it is amending its business model in Asia as part of its initiative to remove complexity from its strategy and concentrate on its main regions.
As per the new strategy, the company aims to shut down its stores and online business in Macau and Hong Kong. Also, Foot Locker plans to transform its stores and e-commerce operations in Singapore and Malaysia to a license-based model. However, the company will continue to run stores in South Korea while looking for licensing partners.
The quarterly earnings beat and weak FY 2023 outlook are expected to keep the share price of Foot Locker range-bound in the short term.
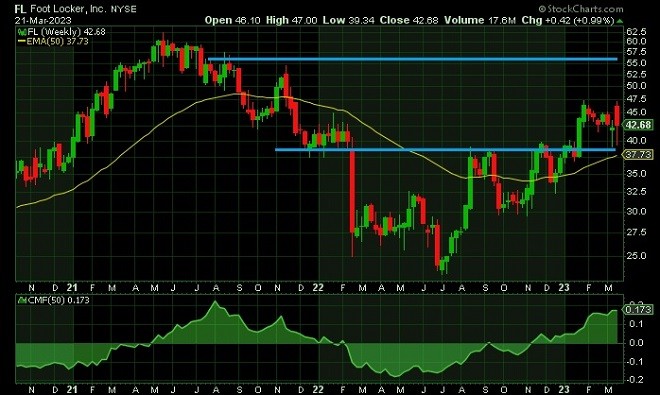
The historical price chart indicates that the stock of Foot Locker is rising after testing the support at 37. The next resistance is anticipated only near 57. Additionally, the stock of Foot Locker is trading above its 50-day moving average, while the Chaikin Money Flow indicator is showing a positive reading. Therefore, we anticipate the share price of Foot Locker to remain in an uptrend in the days ahead.
Disclaimer: Any financial trading analysis offered here is our opinion and is not intended as advice or direction for investors. We cannot guarantee the success of any trades made as a consequence of this article, and we encourage traders to incorporate a strong money management strategy to limit losses when they enter the markets. Please use this article as part of your own research before formulating strategies prior to trading.