Information technology solutions provider Dell Technologies Inc (NYSE: DELL) reported better than anticipated fiscal 2023 third-quarter results. However, the company issued weak Q4 earnings and revenue guidance. This took a toll on the share price, which lost 6.77% or $2.78 to close at $43.85.
The Round Rock, Texas-based company reported third-quarter revenues of $24.72 billion, a decline of 6% from $26.42 billion in the similar quarter of fiscal 2022. Products revenues fell by 10% y-o-y to $18.94 billion. Services revenues were $5.78 billion, up 6% from last year.
For the latest quarter, which ended October 28, 2022, the multi-cloud and big data solutions provider reported a net income from continuing operations of $245 million, or $0.33 per share, a sharp decline from $3.68 billion, or $4.68 per share, in the quarter ended October 29, 2021.
Excluding amortization of intangibles, stock-based compensation expense, other corporate expenses, the impact of purchase accounting, fair value adjustments on equity investments, and aggregate adjustments for income taxes, among others, Dell’s 3Q23 non-GAAP earnings were $1.71 billion, or $2.30 per share, compared with non-GAAP earnings of $1.312 billion, or $1.66 per share, in 3Q22. Analysts polled by FactSet had anticipated earnings of $1.60 per share on revenues of $24.37 billion.
Commenting on the results, Chuck Whitten, co-chief operating officer, of Dell Technologies, stated “We executed Q3 with focus and delivered strong operating results, successfully navigating the challenging environment we highlighted in our Q2 earnings call.”
Segment wise,
- Infrastructure solutions group (ISG) revenues surged 12% y-o-y to $9.630 billion and surpassed forecasts of $9.48 billion. Specifically, servers and networking revenues were $5.201 billion, up 14% from the prior-year period. Storage revenues were $4.429 billion, an increase of 11% from last year.
- Client solutions group (CSG or PC division) revenues fell by 17% y-o-y to $13.78 billion and missed Street’s expectation of $13.93 billion. In particular, commercial revenues declined 13% to $10.75 billion, but surpassed forecasts of $10.55 billion. Consumer revenues slumped by 29% to $3.03 billion, but exceeded analysts’ expectations of $2.98 billion.
During the earnings call, Tom Sweet, chief financial officer, stated that the company anticipates Q4 revenues in the range of $23 billion to $24 billion, reflecting a 16% decline from midpoints. Dell also projected ISG revenues to remain almost flat. Additionally, Q4 earnings are expected to be between $1.50 and $1.80 per share, reflecting a drop of 4% from the midpoint.
Analysts forecast the advanced storage solutions provider to report Q4 earnings of $1.63 per share on revenues of $24.87 billion.
For FY 2023, the company expects revenues of between $100.26 billion and $101.26 billion. Wall Street analysts anticipate revenues of $101.84 billion.
The earnings beat and weak Q4 FY 2023 outlook are expected to keep the share price of Dell range bound in the short term.
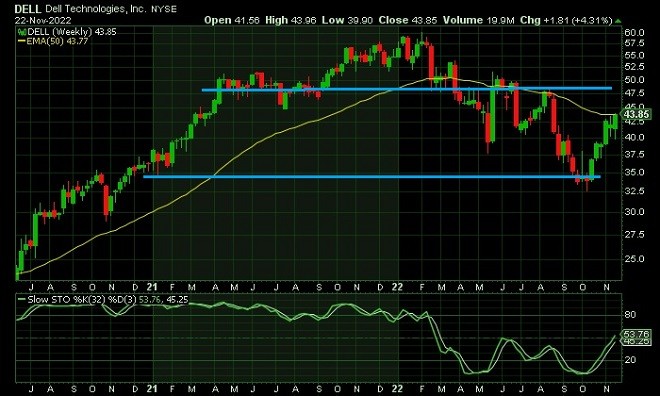
The historical price chart indicates that the stock of Dell is rising after testing the support at 35. The next resistance is anticipated only near 48. Additionally, the stock has closed above its 50-day moving average while the stochastic indicator is rising. Therefore, we anticipate the share price of Dell to increase further in the days ahead.
Disclaimer: Any financial trading analysis offered here is our opinion and is not intended as advice or direction for investors. We cannot guarantee the success of any trades made as a consequence of this article, and we encourage traders to incorporate a strong money management strategy to limit losses when they enter the markets. Please use this article as part of your own research before formulating strategies prior to trading.