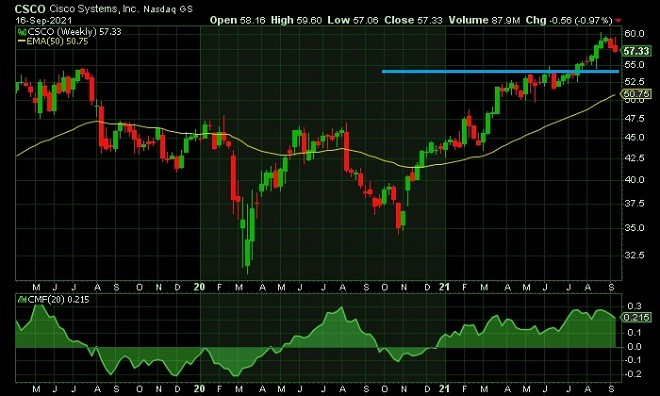
The stock of Cisco Systems Inc (Nasdaq: CSCO) garnered the market’s attention Thursday after Sami Badri, an analyst at Credit Suisse, upgraded its rating to “outperform” from “Neutral.” In a note to clients, the analyst had stated that the networking solutions provider is on course to meet its long-term objectives, which will spark a substantial uptrend in the stock’s price. The stock ended Thursday’s trading session at $57.33, almost flat from the prior close.
The San Jose, California-based company anticipates generating roughly 50% of its revenues from software and other kinds of recurring sales by 2025. The company’s CFO (Chief Financial Officer), Scott Herren, has stated that Cisco’s subscription revenue would be generated from services offered at low margins compared with software.
Nevertheless, the increase in semi-conductor prices is forecast to have a negative impact on the aggregate profits and margins in the hardware business. Notably, Taiwan Semiconductor Manufacturing Co Ltd has recently increased the price of the chips it offers to Cisco by 8% to 20%.
The company is slowly decreasing its revenue dependence on the sale of networking equipment to corporate offices and data centers by realigning its business operations towards selling subscription software such as WebEx collaboration service and cybersecurity-related services. In this regard, the company believes that its subscription revenue will account for 50% of total revenue by FY 2025, from the level of 44% recorded in FY 2021.
Furthermore, Cisco projects FY 2025 revenue of $62.90 billion (mid-point of the range), reflecting a CAGR (compounded Annual Growth Rate) of between 5% and 7%. The company also anticipates a comparable growth rate for adjusted earnings per share, translating to $0.47 (mid-point) in FY 2025.
For the current quarter (1Q 2022), Cisco forecast revenue growth of 7.50% to 9.50% and non-GAAP earnings of between $0.79 and $0.81 per share. The non-GAAP gross margin rate is anticipated to be in the range of 63.50% to 64.50%. Also, the non-GAAP operating margin is predicted to be between 31.50% and 32.50%.
For FY 2022, the company expects revenue growth in the range of 5% to 7% and non-GAAP earnings of between $3.38 per share and $3.45 per share (reflecting a y-o-y increase in the range of 5% to 7%).
According to the analyst, the company is on the right path to achieve the aforesaid objectives. While upgrading the stock, Sam Badri lifted the stock’s price target to $74, from the earlier level of $56, reflecting an upside of about 28% from yesterday’s close.
The “outperform” rating is expected to keep the stock bullish in the short term.
The historical price chart indicates that the stock has solid support at 55. Furthermore, the Chaikin money flow indicator has a positive reading. Therefore, we are anticipating the stock to remain in an uptrend in the short term.
Disclaimer: Any financial trading analysis offered here is our opinion and is not intended as advice or direction for investors. We cannot guarantee the success of any trades made as a consequence of this article, and we encourage traders to incorporate a strong money management strategy to limit losses when they enter the markets. Please use this article as part of your own research before formulating strategies prior to trading.