Cisco Systems Inc. (Nasdaq: CSCO) reported better-than-anticipated fiscal 2024 first-quarter earnings and revenues. However, the networking equipment provider issued a lower-than-anticipated second-quarter outlook. Additionally, the company also downwardly revised its FY 2024 guidance. This triggered a sell of the stock, which ended Friday’s trading session at $47.76, almost unchanged from its prior close.
The San Jose, California-based company reported first-quarter revenues of $14.67 billion, an increase of 7.60% from $13.63 billion in the comparable quarter of fiscal 2023.
For the first quarter, which ended October 28, 2023, Cisco posted earnings of $3.64 billion, or $0.89 per share, compared with $2.67 billion, or $0.65 per share, in the quarter ended October 29, 2022.
Excluding share-based compensation expense, amortization of acquisition-related intangible assets, and acquisition-related/divestiture costs, among others, Cisco recorded 1Q 2024 non-GAAP earnings of $4.53 billion, or $1.11 per share, an increase from $3.55 billion, or $0.86 per share, in 1Q 2023.
Analysts surveyed by LSEG had anticipated the company to report non-GAAP earnings of $1.11 per share on revenues of $14.61 billion.
Segment wise:
- Product revenues grew by 9% y-o-y to $11.14 billion.
- Specifically, Networking revenues surged 10% y-o-y to $8.82 billion.
- Security revenues were $1.01 billion, up 4% on a y-o-y basis.
- Collaboration revenues increased by 3% to $1.12 billion.
- Services revenues were $3.53 billion, an increase of 4% from last year.
Looking ahead, Cisco forecasts fiscal 2024 second-quarter revenues in the range of $12.60 billion to $12.80 billion. The company also projects 2Q 2024 non-GAAP earnings of between $0.82 and $0.84 per share. Analysts surveyed by LSEG anticipate Cisco to post adjusted earnings of $0.99 per share on revenues of $14.19 billion.
For fiscal 2024, the company now expects non-GAAP earnings in the range of $3.87 to $3.93 per share on revenues of $53.80 billion to $55 billion. Cisco’s earlier guidance had forecast non-GAAP earnings of $4.01 to $4.08 per share on revenues of between $57 billion and $58.20 billion.
In an attempt to strengthen its portfolio of products, Cisco agreed to take over data-crunching software developer Splunk Inc. for $28 billion in September. The takeover deal is expected to be completed in 3Q 2024. Recurring sales represent 44% of Cisco’s total revenues. The acquisition, as per the company, will further boost recurring sales.
The company also underlined the gains from investing in AI solutions. Cisco revealed that it has a backlog of $1 billion worth of orders related to AI, up 100% from the previous quarter.
The quarterly earnings beat and weak outlook are expected to keep Cisco’s stock range-bound in the short term.
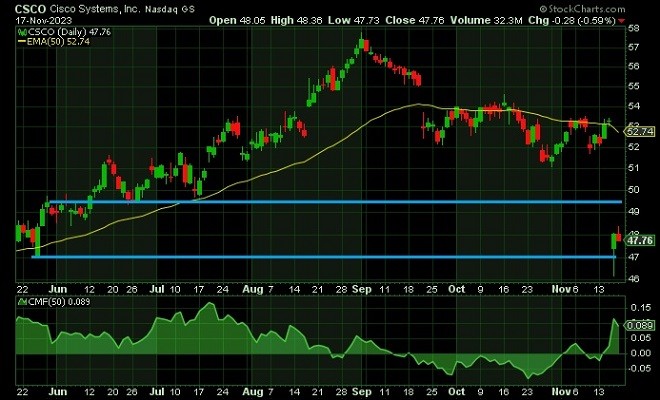
The historical price chart indicates that the stock of Cisco is rising after consolidating at the $47 level. The next resistance is anticipated to be only near $50. Additionally, the stock is trading above its 50-day moving average, while the Chaikin Money Flow indicator is showing a positive reading. Therefore, we anticipate Cisco’s stock to remain in an uptrend in the near term.
Disclaimer: Any financial trading analysis offered here is our opinion and is not intended as advice or direction for investors. We cannot guarantee the success of any trades made as a consequence of this article, and we encourage traders to incorporate a strong money management strategy to limit losses when they enter the markets. Please use this article as part of your own research before formulating strategies prior to trading.