Networking products manufacturer Cisco Systems Inc (Nasdaq: CSCO) reported better-than-anticipated fiscal 2021 third-quarter earnings and revenue.
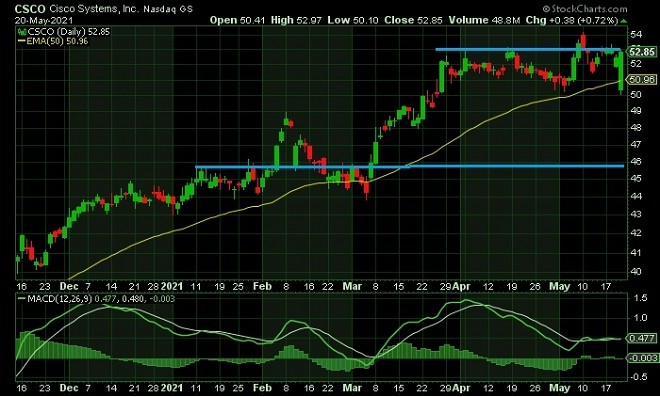
However, the company issued a lower-than-anticipated Q4 outlook, citing pressure on profit margins due to supply chain issues. Following the weak guidance, the stock closed at $52.85, up to $0.38 or 0.72% from the previous close.
San Jose, a California-based company, reported third-quarter revenue of $12.803 billion, compared with $11.983 billion in a similar period last year. Notably, the reported figure reflects the first revenue growth after five successive quarters of revenue declines.
For the quarter ended May first, 2021, Cisco posted 3Q 2021 net income of $2.863 billion or $0.68 p/s, a slight increase from $2.774 billion, or $0.65 a share ended April 25 2020.
Share-based compensation expense, amortization of acquisition-related intangible assets, and legal and indemnification settlements/charges, among others, the company recorded Q3 2021 non-GAAP net income of $3.510 billion, or $0.83 per share, an increase from $3.368 billion, or $0.79 per share in Q3 2020.
Analysts surveyed by Refinitiv had anticipated the company to report earnings of $0.82 per share on revenues of $12.56 billion.
Commenting on the results, Chuck Robbins, chairman and CEO of Cisco, said, “Cisco had a great quarter with strong demand across the business. We are confident in our strategy and our ability to lead the next phase of the recovery as our customers accelerate their adoption of hybrid work, digital transformation, cloud, and continued strong uptake of our subscription-based offerings.”
Segment-wise,
- Product revenues increased 6.3% y-o-y to $9.139 billion in 3Q 2021.
- Service revenues were $3.664 billion, an increase of 8.2% from last year.
Product-wise,
- Infrastructure Platforms revenues rose 6% y-o-y to $6.832 billion. Analysts surveyed by FactSet had anticipated revenues of $6.77 billion.
- Applications revenues were $1.426, up 5% from the prior-year period, but missed the $1.44 billion FactSet consensus.
- Security revenues increased 13% to $876 million.
The company also reported 10% y-o-y aggregate product order growth reflecting the most robust demand in almost a decade. Cisco also reported continued momentum in shifting business to software and related subscriptions. Specifically, subscriptions accounted for 81% of software revenue, increasing from 76% in 2Q 2021.
On a GAAP basis, aggregate gross margin, gross product margin, and services gross margin were 63.9%, 62.6%, and 67.4%, respectively. This compares with 64.9%, 63.7%, and 67.7%, respectively, in 3Q20.
Cash flow from operating activities was $3.90 billion in 3Q 2021, down 8% from 4.20 billion in 3Q 2020.
Looking ahead, Cisco anticipates Q4 revenue growth of between 6% and 8% on a y-o-y basis. The company also forecasts GAAP earnings to be in the range of $0.64 per share to $0.69 per share.
Non-GAAP earnings are anticipated to be between $0.81 and $0.83 per share. Analysts had anticipated the company to report adjusted earnings of $0.85 per share on $12.82 billion in revenues, reflecting a growth of 5.50%.
Cisco completed its $4.50 billion takeovers of networking hardware equipment manufacturer Acacia Communications during the third quarter.
Also, the company finished acquiring IMImobile, a communications software firm, for $730 million. This is in addition to the acquisition of Dashbase Inc., an enterprise software firm, for an undisclosed amount.
In the current quarter, the company has completed Slido s.r.o, a privately held firm offering an audience interaction platform.
During the third quarter, the company returned $2.10 billion to stockholders via share repurchases and dividends.
Specifically, the company paid a cash dividend of $0.37 per share ($1.60 billion) and bought back roughly 10 million shares for $510 million, reflecting an average purchase price of $48.71 per share. The company also has stock repurchase authorization for $8.70 billion.
The quarterly earnings beat and weak Q4 outlook are expected to keep the stock range-bound with a slight bearish bias.
The historical price chart indicates that the stock is facing resistance at 53. The following support is anticipated only near 46. Additionally, the stock is trading below its 50-day moving average, while the MACD indicator has a negative reading. Therefore, we are anticipating the stock to remain in a downtrend in the short term.
Disclaimer: Any financial trading analysis offered here is our opinion and is not intended as advice or direction for investors. We cannot guarantee the success of any trades made as a consequence of this article, and we encourage traders to incorporate a strong money management strategy to limit losses when they enter the markets. Please use this article as part of your own research before formulating strategies prior to trading.