Dell Technologies Inc (NYSE: DELL) reported better-than-anticipated fiscal 2023 fourth-quarter earnings and revenues. However, the company’s FY 2024 revenue and earnings outlook missed the Street consensus. The stock closed Friday’s trading session at $39.79, down $0.38 or 0.95% from the previous day’s close.
The Round Rock, Texas-based company posted fourth-quarter revenues of $25.04 billion, down 11% from $27.99 billion in the comparable period last year. The quarterly revenue exceeded the company’s top-line guidance range of between $23 billion and $24 billion and Refinitiv’s forecast of $23.40 billion.
For the fourth quarter, which ended February 3, 2023, Dell recorded net income from continuing operations of $606 million, or $0.84 per share, rebounding from a net loss of $29 million, or $0.04 per share, in the quarter ended January 28, 2022.
Amortization of intangibles, the impact of purchase accounting, transaction-related (income) expenses, stock-based compensation expense, other corporate expenses, fair value adjustments on equity investments, and aggregate adjustments for income taxes, among others, the company reported Q4 2023 non-GAAP net income of $1.32 billion, or $1.80 per share, compared with a non-GAAP net income of $1.39 billion, or $1.72 per share, in Q4 2022.
The company’s quarterly earnings exceeded Dell’s projections of $1.50 to $1.80 per share and Wall Street forecasts of $1.63 per share.
Jeff Clarke, vice chairman and co-chief operating officer of Dell Technologies, stated “Our end-to-end portfolio is a proven competitive advantage in this changing environment.”
Segment wise:
- Products revenues fell by 15% y-o-y to $19.04 billion.
- Services revenues were $6 billion, up 9% from last year.
By nature of business:
Infrastructure Solutions Group (ISG) revenues grew by 7%y-o-y to $9.91 billion and exceeded forecasts of $9.40 billion.
- Servers and networking revenues inched up 5% y-o-y to $4.94 billion.
- Storage revenues were $4.97 billion, an increase of 10% from the previous year.
Client Solutions Group (CSG) revenues plunged 23% y-o-y to $13.36 billion but surpassed the Street Consensus of $12.30 billion.
- Commercial revenues fell by 17% y-o-y to $10.70 billion.
- Consumer revenues dipped 40% y-o-y to $2.66 billion.
Tom Sweet, chief financial officer at Dell Technologies, stated that the company anticipates the current quarter (1Q 2024) top line to be below average compared to what it used to be during this period. Specifically, Sweet projected revenue to decrease 17% to 21% on a sequential basis, implying revenue of $20.75 billion (the mid-point of the range) and below the consensus estimate of $21.60 billion. Dell forecasts a headwind of roughly 3% as an outcome of currency conversion rates in the current quarter.
Furthermore, Sweet states that the ISG division will record a 20% decline in revenue on a sequential basis. Likewise, the company expects the CSG division to post a mid-teens decline in revenue on a q-o-q basis. Overall, Dell expects Q1 earnings of $0.80 per share (+/- $0.15 per share), missing the consensus estimate of $1.25 per share.
For FY 2024, Dell projects a revenue decline in the range of 12% to 18%, missing the Street consensus calling for a drop of 9.60%. The company’s guidance implies revenues of $87 billion, reflecting a 15% drop on a midpoint basis. Dell also expects FY 2024 earnings of $5.30 per share (+/- $0.30 per share), missing the Wall Street consensus of $6.37 per share.
Notably, at the end of 2Q 2024, Tom Sweet, who has served the company for 26 years, will step down. He will be succeeded by Yvonne McGill, Dell’s corporate controller, who has been serving Dell for 25 years in several roles. The company also declared a quarterly dividend of $0.37 per share, reflecting an increase of 12%. Dell repurchased $260 million worth of shares in the latest quarter, bringing the total value of repurchases to $2.80 billion.
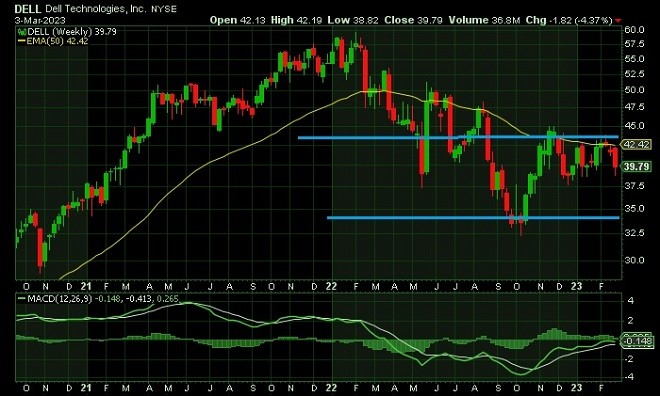
The quarterly earnings beat and slightly weaker Q1 and FY 2024 outlook are expected to keep the share price of Dell range-bound in the short term.
The historical price chart indicates that the stock of Dell is declining after facing resistance at 44. The next major support is anticipated only near 32. Additionally, the stock is trading below its 50-day moving average, while the MACD indicator is showing a negative reading. Therefore, we anticipate the stock to remain in a downtrend in the near term.
Disclaimer: Any financial trading analysis offered here is our opinion and is not intended as advice or direction for investors. We cannot guarantee the success of any trades made as a consequence of this article, and we encourage traders to incorporate a strong money management strategy to limit losses when they enter the markets. Please use this article as part of your own research before formulating strategies prior to trading.