The pound declined against the greenback yesterday following the Fed’s decision to lift benchmark interest rates by 75bps. The Fed also maintained its hawkish stance and upwardly amended its cash rate projections for this year and 2023. Overall, the GBP/USD pair fell from a high of 1.1280 to a low of 1.1220 in the last 24 hours.
According to the ONS (Office for National Statistics), the UK’s public sector net borrowing, devoid of public sector banks, was £11.8 billion in August 2022, up from £2.10 billion in July, and higher than forecasts of £8.20 billion.
However, the reported figure is £2.60 billion lower than the August 2021 level, but £6.50 billion higher than the pre-Covid-19 August 2019 level of £5.30 billion.
The UK’s central government debt interest payable was £8.20 billion in August 2022, mirroring the highest figure since April 1997 and being £1.50 billion higher than August 2021. In August 2022, the government receipts stood at £69.60 billion, £5.60 billion higher than in August 2021.
The net cash requirement of the central government was £4.90 billion in August 2022, a decrease of £3.60 billion from an £8.50 billion cash deficit recorded in August 2021.
Public sector net debt, devoid of public sector banks, was £2.427 trillion (representing 96.60% of GDP) in August 2022, reflecting a rise of £195.20 billion (or 1.90% of GDP) from its August 2021 level.
The Confederation of British Industry’s order book expectations index improved to -2 in September, from -7 in the prior month. Economists had anticipated a worsening of the order book expectations index to -11.
The export order book index improved to -8 in September from -12 in August. However, output growth is anticipated to slow considerably over the forthcoming three months, with the corresponding index worsening to -17 in September, from -2 in August. The index reflecting stocks of finished goods rose to 6, from 2. Expectations regarding inflation pressures grew to 59, from 57.
According to the National Association of Realtors, US existing home sales inched down to 4.80 million units in August, from 4.81 million units in the prior month, but surpassed forecasts of 4.69 million units. The reported figure reflects the seventh successive monthly decrease.
On a year-on-year basis, sales plunged 19.90% from 5.99 million units in August 2021.
Aggregate housing inventory was 1.28 million units in August, a decline of 1.50% from July, but unaltered from the prior year. The reported figure also reflects the first decline after five consecutive monthly increases. Unsold inventory remains at a 3.2-month supply at the prevailing rate of sales in August, unaltered from the prior month.
Later in the US session, the Fed lifted its benchmark interest rate by 75bps to a range of between 3% and 3.25%. More importantly, the Fed signaled further steep rate hikes, with the latest forecasts reflecting a policy rate increasing to 4.40% by the end of 2022 and hitting a peak of 4.60% by next year to contain inflationary pressures.
The Fed rate hike and hawkish stance are expected to keep the US dollar bullish against its peers, including the pound, in the near term.
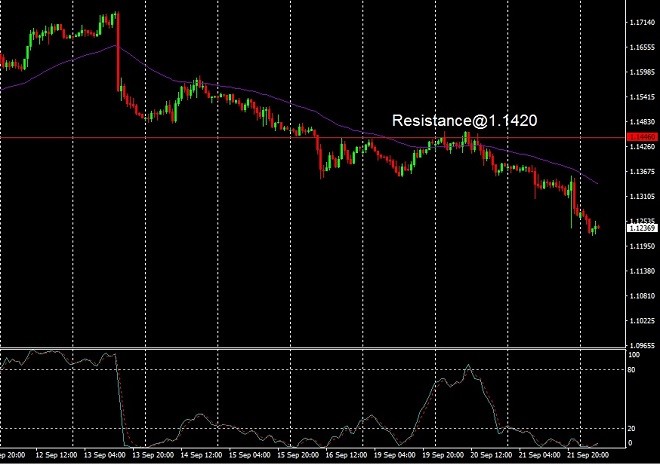
Technically, the GBP/USD pair is declining after facing resistance at 1.1420. The next major support is anticipated only near 1.10 levels. The currency pair is trading below its 50-day moving average while the stochastics indicator is in the bearish zone. Therefore, we anticipate the currency pair to remain in a downtrend in the near term.
Disclaimer: Any financial trading analysis offered here is our opinion and is not intended as advice or direction for investors. We cannot guarantee the success of any trades made as a consequence of this article, and we encourage traders to incorporate a strong money management strategy to limit losses when they enter the markets. Please use this article as part of your own research before formulating strategies prior to trading.